
U.S. Warehouse Construction Surges 18% as Data-Center Supply Chains Drive Industrial Real Estate
Industrial real estate construction reached 305 million square feet in the second quarter of 2026, ending a prolonged post-pandemic slump. The rebound is being driven not by e-commerce, but by the massive staging requirements of the AI and data-center supply chain.
By Tao Yang
Share this story
The U.S. industrial real estate market has officially snapped its post-pandemic slump, driven by an unexpected new anchor. In the second quarter of 2026, warehouse and industrial space under construction surged 18 percent year-over-year, reaching more than 305 million square feet. This marks the second consecutive quarter of pipeline growth, signaling that developers have deployed capital with renewed conviction after a prolonged period of frozen groundbreakings.[1][2][3]
But the catalyst for this rebound is not the traditional cast of e-commerce giants or third-party logistics providers that defined the 2021 building boom. Instead, the surge is being overwhelmingly driven by the physical supply chain required to build artificial intelligence infrastructure. Data-center equipment suppliers have emerged as the primary source of new bulk industrial demand, fundamentally reshaping where and why warehouses are built.[1]
To understand this shift, one must look at the sheer scale of the hardware required for modern computing. Hyperscalers—the major cloud service providers—are projected to spend more than $725 billion in capital expenditures in 2026 alone, a massive acceleration sparked by the generative AI arms race. While much of that capital buys advanced microchips and servers, a significant portion flows into the industrial sector to procure the power, cooling, and physical infrastructure needed to keep those servers running.[4]
Delivering that infrastructure requires massive staging grounds. Data centers are highly complex, multi-year construction projects that rely on specialized equipment with notoriously long lead times. Power transformers and switchgear currently face delivery delays of three to five years, while large backup generators require 72 to 96 weeks from order to delivery.[4]
Contractors and specialty suppliers cannot simply drop multi-million-dollar electrical components onto a dirt lot while waiting for a data center's foundation to be poured. They require secure, climate-controlled, heavy-floor-load industrial space near the active build sites to receive, stage, pre-configure, and eventually ship hardware to the final campus.[1]
This staging requirement has tightly coupled the logistics real estate market to the data-center boom. Suppliers need short-to-medium-term industrial commitments near major development corridors, pulling new warehouse product to locations that traditional distribution users historically ignored.[1]
The geographic concentration of this demand is stark. Markets with heavy data-center construction activity—such as Northern Virginia, the Phoenix metropolitan area, and parts of Texas—are seeing intense leasing competition and tightening vacancy rates. In these specific corridors, the influx of tech-adjacent suppliers is absorbing space rapidly, giving landlords renewed pricing power.[1]
Conversely, the national aggregate of 305 million square feet masks significant regional divergence. Industrial markets that lack a strong data-center pipeline are still working through the excess vacancy created during the 2023 and 2024 delivery waves. For operations leaders evaluating their distribution footprints, the headline construction number does not mean every submarket is booming equally.[1]
The nature of the buildings themselves is also evolving to meet this new tenant profile. The fundamental valuation of industrial commercial real estate is shifting, with electrical capacity rapidly becoming a primary value driver alongside sheer square footage.[5]
In some specialized sub-sectors, the pricing model has entirely decoupled from traditional real estate metrics. Facilities are increasingly evaluated on available power delivery, and pricing structures in highly constrained markets have begun shifting from dollars per square foot to dollars per kilowatt-month. This reflects a reality where physical space is abundant, but the electricity required to test and configure high-density server racks is a scarce resource.[5]
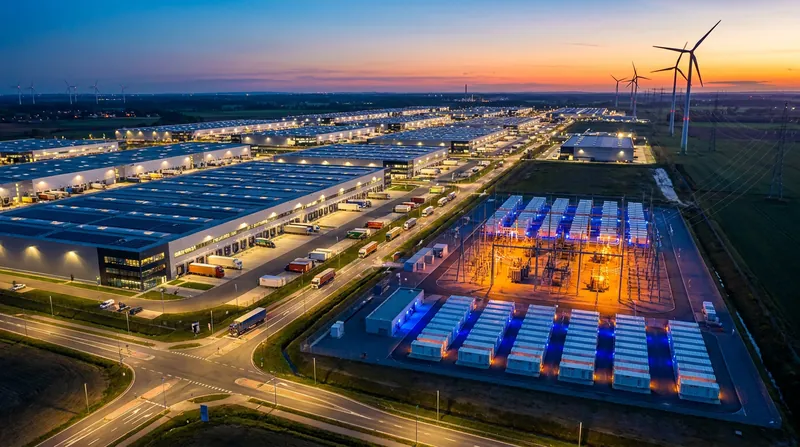
Power and water availability remain the most significant bottlenecks constraining further development. Even as developers rush to break ground on new warehouses to serve the tech supply chain, they face multi-year interconnection queues with local utilities.[5]
In response, industrial developers are increasingly pursuing on-site power generation. Investments in combined heat and power systems, microgrids, and utility-scale battery storage are becoming standard features for premium industrial parks, providing timeline certainty when municipal grid upgrades lag years behind commercial demand.[5]
The timeline of this new construction wave offers a window into the industry's long-term expectations. Because new industrial product typically delivers 18 to 24 months after a groundbreaking, the projects starting in the second quarter of 2026 will not hit the market until late 2027 or 2028.[1]
By committing capital today, developers are effectively betting that the hyperscaler infrastructure buildout will sustain its current velocity well into the end of the decade. They are pricing in the assumption that AI monetization will justify the continued deployment of multi-billion-dollar campuses, and by extension, the warehouses needed to supply them.[1][4]
For traditional supply-chain and logistics leaders, this tech-driven pipeline shift changes the negotiating environment. Companies looking to lease standard distribution space in markets where data-center supply chains are concentrating may find themselves competing against well-capitalized tech suppliers for the same square footage.[1]
Ultimately, the 18 percent surge in warehouse construction proves that the industrial real estate sector has successfully pivoted. No longer solely dependent on the ebb and flow of consumer e-commerce, the asset class has found a new, highly capitalized foundation as the physical backbone of the artificial intelligence economy.[1][2]
Key points
- U.S. warehouse construction surged 18% year-over-year in Q2 2026, reaching 305 million square feet.
- The rebound is driven not by e-commerce, but by the need to stage equipment for new data centers.
- Suppliers require massive industrial spaces to stockpile transformers and generators that have multi-year lead times.
- Demand is highly concentrated in active tech corridors like Northern Virginia, Phoenix, and Texas.
What we don’t know
- Whether the current pace of hyperscaler capital expenditure will sustain through the end of the decade to absorb the new warehouse supply.
- How local utility grids will manage the compounding power demands of both the data centers and the industrial facilities supporting them.
- To what extent traditional logistics tenants will be priced out of primary markets by well-capitalized tech suppliers.
How we got here
2021-2022
E-commerce demand drives a massive boom in speculative warehouse construction across the United States.
2023-2024
Post-pandemic oversupply and rising interest rates cause a prolonged slump in new industrial groundbreakings.
Late 2024
Generative AI triggers a massive surge in hyperscaler capital expenditure, kicking off a new wave of data center development.
Q1 2026
U.S. warehouse construction records its first quarter of year-over-year growth since the downturn, signaling a market inflection.
Q2 2026
Industrial construction surges 18 percent year-over-year to 305 million square feet, firmly anchored by data-center supply chain demand.
- Hyperscalers & Suppliers
- View industrial real estate as a critical bottleneck for AI deployment, requiring massive staging areas to manage multi-year equipment lead times.
- Industrial Developers
- Focus on deploying capital to meet the new demand from tech infrastructure, prioritizing markets with available power.
- Traditional Logistics Tenants
- Concerned about competing for space and facing higher rents in key corridors as tech companies absorb available warehouse inventory.
Perspectives this story doesn't cover
- Local utility operators managing the grid strain
- Municipal zoning boards balancing industrial growth with community concerns
Sources
Source coverage
5 outlets
3 viewpoints surfaced

- [1]MarketScaleTraditional Logistics Tenants
U.S. warehouse construction jumps 18% as data-center supply chains drive industrial real estate
- [2]The Wall Street JournalHyperscalers & Suppliers
Warehouse Construction Surges as Data Centers Drive Demand
Read on The Wall Street Journal → - [3]Cushman & WakefieldIndustrial Developers
Q2 2026 Industrial Real Estate Marketbeat
Read on Cushman & Wakefield → - [4]RSM USHyperscalers & Suppliers
Industrial supply base responds to data center boom
- [5]SVN Masiello GroupIndustrial Developers
The changing fundamentals of industrial commercial real estate
More in Real Estate
See all →Investment Vehicles
Why REITs Must Distribute 90% of Taxable Income to Bypass Corporate Taxes
7 sources
Lease Mechanics
How Gross, Net, and Percentage Commercial Leases Divide Property Costs and Risk
6 sources
Delaware Statutory Trusts
Delaware Statutory Trusts: Deferring Capital Gains Through Fractional Property Ownership
5 sources
Medical Real Estate
Medical Office Assets Appreciate 67% Since 2024, Decoupling Sector From Traditional Office Market Distress
3 sources
Comments
Every angle. Every day.
Get Real Estate stories with full source coverage and perspective breakdowns, free every day.