
Data Center Boom Masks General CRE Construction Slowdown to Post-Recession Levels
A historic surge in data center development is single-handedly propping up national construction metrics, concealing a deep contraction in traditional commercial real estate.
- Commercial Real Estate Analysts
- Warns that headline construction growth is an illusion masking deep structural weakness in traditional property sectors.
- Digital Infrastructure Investors
- Views the data center boom as a fundamental shift in the economy, treating digital facilities as mission-critical infrastructure.
- Local Economic Planners
- Balances the massive capital investment and job creation of data centers against the strain on local power grids and construction labor.
Perspectives this story doesn't cover
- Traditional Office Landlords
- Small Commercial Contractors
- 92%
- Share of office-category construction dollars now going to data centers
- 66 GW
- Data center capacity under construction in North America
- 77%
- Share of new capacity being built in frontier markets
- 14.4%
- Share of industrial leasing tied to data center supply chains in major hubs
If you are a local contractor, a warehouse operator, or a commercial landlord, the headline construction numbers for 2026 look robust, suggesting a healthy market for commercial real estate development. But for anyone not building a massive server farm, the reality on the ground feels entirely different.[1]
A historic boom in data center construction—driven by the insatiable demands of artificial intelligence and cloud computing—is single-handedly propping up national nonresidential building figures. Strip away the data centers, and traditional commercial construction has slowed to a crawl not seen since the aftermath of the Great Recession.[2]
The data from Wells Fargo's mid-year 2026 outlook confirms this stark divergence. While overall transaction volumes have shown some resilience, new construction starts for traditional assets like offices and retail have plummeted.[2]
ConstructConnect's analysis provides the exact math behind the illusion. Data centers now account for a staggering 22% of all nonresidential building starts. Even more dramatically, they represent 92% of all construction dollars within the "office" category, completely masking the ongoing collapse of traditional office development.[1]
For local tradespeople and regional suppliers, this concentration means that unless they are positioned to service hyperscale tech projects, the broader market is shrinking. Removing the data center category from national forecasts flips the outlook from a modest 1.5% growth to a near 9% contraction.[1]
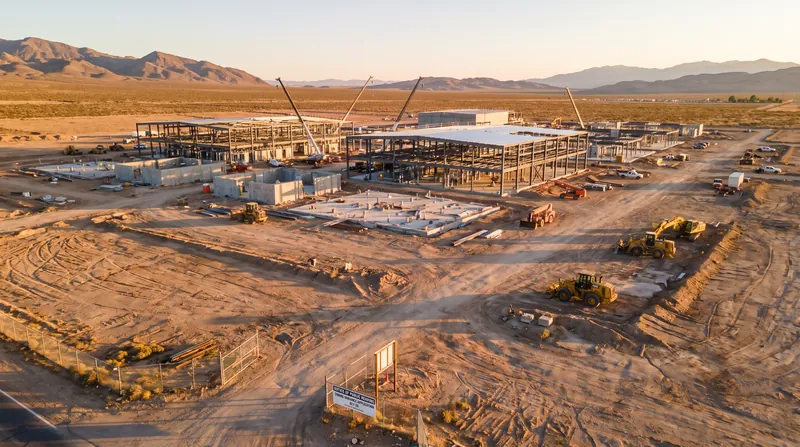
The scale of the data center build-out is unprecedented. According to JLL, more than 66 gigawatts of capacity are currently under construction in North America. To put that in perspective, this represents an electricity requirement greater than the entire country of Germany.[3]
This capacity isn't just concentrated in traditional hubs like Northern Virginia. The geographic footprint is shifting rapidly. JLL data shows that 77% of new capacity is being built in "frontier markets"—places like West Texas, Ohio, Indiana, and the Carolinas, which had almost no data center presence a decade ago.[3]
This capacity isn't just concentrated in traditional hubs like Northern Virginia.
For these local communities, the influx brings massive capital investment and property tax revenue. Research from Georgia Tech indicates that when a data center opens, the host county sees a measurable lift: employment rises by about 3.5% and wages by 5%.[7]
However, the sheer scale of these billion-dollar megaprojects fundamentally alters regional construction economies, absorbing available labor and materials while straining local power grids.[7]
The ripple effects extend beyond the data centers themselves. A recent report from Cushman & Wakefield highlights how this boom is generating secondary demand for industrial real estate. Electrical contractors, cooling equipment manufacturers, and logistics firms supporting these facilities need their own warehouse space.[4]
In major data center hubs, these related tenants accounted for a record 14.4% of all new industrial leasing in the past year. For industrial landlords and local businesses, this creates a lucrative micro-economy tethered entirely to digital infrastructure.[4]
Yet the broader commercial market remains weighed down by high interest rates and shifting work habits. The Seattle Daily Journal of Commerce reported that while nonresidential spending ticked up slightly in June 2026, the underlying private-sector demand for traditional retail, hospitality, and office space continues to soften.[5]
The Dodge Construction Network's mid-year data further illustrates the volatility. Total construction starts saw a sharp 19.9% decline in June after a megaproject-heavy May, underscoring how dependent the national metrics have become on a handful of massive, capital-intensive tech builds rather than broad-based economic expansion.[6]
What remains uncertain is the longevity of this dynamic. ConstructConnect's models suggest data center spending may peak around 2029 or 2030. When that plateau arrives, the underlying weakness of the broader commercial market will be fully exposed unless traditional sectors have recovered by then.[1]
For now, the divergence dictates the strategy for anyone in the real estate or construction ecosystem. The headline growth is real, but it is highly specific. Navigating this market requires looking past the national averages and understanding exactly which sectors—and which regions—are actually breaking ground.[8]
What we don’t know
- Whether traditional commercial real estate sectors will recover before data center construction peaks and begins to plateau around 2029.
- How local power grids in frontier markets will handle the unprecedented energy demands of 66 gigawatts of new capacity.
- The long-term impact on local construction costs and labor availability for non-tech projects in regions dominated by data center megaprojects.
Sources
Source coverage
8 outlets
3 viewpoints surfaced




- [1]ConstructConnectCommercial Real Estate Analysts
Headline construction growth masks major disparities across subcategories
Read on ConstructConnect → - [2]Scotsman GuideCommercial Real Estate Analysts
The rise of data centers tied to artificial intelligence remains the biggest news in commercial real estate
Read on Scotsman Guide → - [3]JLLDigital Infrastructure Investors
More than 66 GW of data center capacity is under construction in North America
Read on JLL → - [4]GlobeStDigital Infrastructure Investors
Data center development has become one of the most closely watched issues
Read on GlobeSt → - [5]Seattle Daily Journal of CommerceLocal Economic Planners
Data centers mask broader slowdown as June construction spending stalls
Read on Seattle Daily Journal of Commerce → - [6]Dodge Construction NetworkCommercial Real Estate Analysts
Total construction starts declined 19.9% in June to a seasonally adjusted annual rate
Read on Dodge Construction Network → - [7]Georgia Tech Scheller College of BusinessLocal Economic Planners
Data center construction economic impact
Read on Georgia Tech Scheller College of Business → - [8]Factlen Editorial Team
Synthesis by Factlen editorial team
Read on Factlen Editorial Team →
Comments
More in Real Estate
See all →Mortgage Law
How Recourse and Non-Recourse Mortgage Laws Shape Global Default Risk
5 sources
CMBS Market
US Commercial Real Estate Losses Breach AAA-Rated CMBS Tranches as Treasury Yields Surge
7 sources
AI Infrastructure
World Economic Forum Links $7 Trillion AI Boom to $130 Billion in Stalled Data Center Projects
7 sources
Mortgage Market
Major US Mortgage Lenders Face Collapse as FHA Delinquency Rate Hits 21% for Recent Loans
6 sources
Every angle. Every day.
Get Real Estate stories with full source coverage and perspective breakdowns delivered to your inbox.