
Bipartisan Bill Proposes Fixed, Retroactive 2% Interest Rate for All Federal Student Loans
A bipartisan legislative effort aims to cap all new and existing federal student loan interest rates at a fixed 2 percent, automatically refinancing existing debt to save borrowers thousands.
By Tiago Sousa
Share this story
When most people hear about federal student loan reform, they immediately picture sweeping, trillion-dollar forgiveness programs that inevitably end up stalled in federal courts. The assumption is that any relief must be an all-or-nothing executive action. But the evidence points to a quieter, highly actionable alternative gaining traction in Congress: a bipartisan legislative push to permanently cap all federal student loan interest rates at a fixed 2 percent.
For borrowers currently facing rates as high as 9 percent on federal PLUS loans, this proposal represents a structural shift from managing compounding debt to actually paying down the principal. The legislation—introduced in parallel forms as the Affordable Loans for Students Act and the Lowering Student Loans Act—would retroactively apply a 2 percent interest rate to existing federal loans and lock in that same rate for all future borrowing.[1]
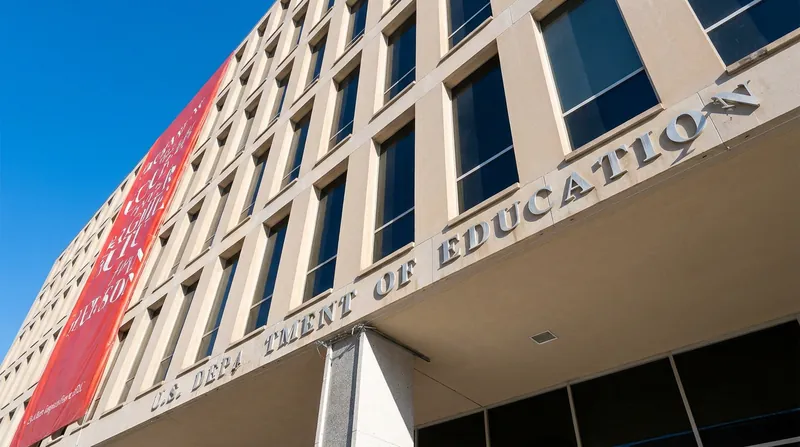
The mechanism of the proposed legislation is designed for utility and immediate impact. Rather than requiring borrowers to navigate complex application portals or consolidate their debt through private lenders, the bill authorizes the Department of Education to automatically modify and refinance eligible federal student loans. Borrowers would not need to opt in to receive the lower rate, though they would retain the right to opt out if they chose.[2]
This 2 percent cap would apply universally across the federal Direct Loan program. That includes undergraduate Stafford loans, unsubsidized loans for graduate students, and Parent PLUS loans, which historically carry the highest borrowing costs. By standardizing the rate, the legislation eliminates the annual recalculation of federal student loan interest, which is currently pegged to the 10-year U.S. Treasury note and set to increase for the 2026–2027 academic year.[1]
The financial evidence supporting the cap highlights substantial long-term savings for the average borrower. Under current conditions, a graduate holding $30,000 in federal student loan debt at a 6.5 percent interest rate pays approximately $345 per month on a standard 10-year repayment plan, totaling over $41,000 by the time the loan is retired. If that same balance were refinanced to a 2 percent rate, the monthly payment would drop, and the total cost of the loan would decrease by nearly $10,000.
Financial aid administrators argue that high interest rates are the primary reason many borrowers make years of on-time payments only to see their total balances grow. By capping the rate at 2 percent, payments are heavily redirected toward the principal balance rather than servicing compounding interest. This structural change helps borrowers build financial stability, qualify for mortgages, and save for retirement much earlier in their careers.[2]
However, there is a specific caveat for borrowers currently enrolled in Income-Driven Repayment (IDR) plans. Because IDR monthly payments are calculated as a percentage of discretionary income rather than being based on the loan's interest rate, a rate reduction to 2 percent would not lower the monthly bill for these individuals. What it would do, instead, is prevent their overall loan balances from ballooning over the 20- to 25-year repayment term, mitigating the tax burden that can occur if a massive forgiven balance is treated as taxable income.[1]
The legislation also addresses borrowers holding older, commercially backed federal debt. Individuals with Federal Family Education Loan (FFEL) program loans or Perkins loans that are not directly held by the Department of Education would be permitted to consolidate those debts into the Direct Loan program. Once consolidated, these loans would immediately qualify for the 2 percent rate without incurring the standard origination fees typically associated with refinancing.[1][2]
Pushing the bill past legislative gridlock remains the primary hurdle. While the proposal enjoys rare bipartisan sponsorship—championed by Republicans like Rep. Mike Lawler and Rep. Anna Paulina Luna alongside Democrats like Rep. Jared Moskowitz and Rep. Mike Thompson—it must still navigate a divided Congress. To bypass leadership delays, a bipartisan coalition recently filed a discharge petition, a procedural maneuver that can force a floor vote if it secures 218 signatures.
This legislative effort arrives at a critical moment for the federal student loan system. With major repayment plans facing legal injunctions and millions of borrowers transitioning back into repayment after pandemic-era pauses, the system is under immense strain. Consumer protection advocates note that stabilizing interest rates provides a baseline level of predictability for families trying to budget for higher education amid ongoing administrative chaos.
For future college students, the 2 percent cap fundamentally alters the return on investment for higher education. By removing the penalty of high borrowing costs, the legislation ensures that taking out federal loans to fund a degree does not result in a lifetime of compounding debt. It shifts the federal student loan program back toward its original intent: facilitating access to education rather than generating revenue through interest yields.[2]
Ultimately, the push for a fixed 2 percent interest rate represents a pragmatic pivot in higher education policy. Rather than waiting for sweeping forgiveness that may never materialize, lawmakers and financial aid experts are focusing on a mathematical fix that immediately lowers the cost of borrowing. If enacted, it would provide guaranteed, retroactive relief that fundamentally changes how Americans finance their education.[2]
Key points
- Bipartisan legislation proposes a fixed 2 percent interest rate for all new and existing federal student loans.
- The Department of Education would automatically refinance eligible loans without requiring borrowers to opt in.
- The cap applies universally to undergraduate, graduate, and Parent PLUS loans.
- Borrowers with older FFEL loans could consolidate into the Direct Loan program to access the lower rate.
Open questions
- Whether the discharge petition will secure the 218 signatures required to force a floor vote in the House.
- How the legislation would interact with ongoing legal battles surrounding federal Income-Driven Repayment (IDR) plans.
- The exact timeline for the Department of Education to implement the automatic refinancing if the bill is signed into law.
Timeline
March 2025
The Affordable Loans for Students Act is introduced, proposing a 2 percent interest rate cap.
March 2026
The Lowering Student Loans Act is introduced as a parallel effort to secure the 2 percent fixed rate.
June 2026
A bipartisan coalition files a discharge petition to bypass House leadership and force a floor vote on the legislation.
- Bipartisan Lawmakers
- Argue that capping interest rates is a pragmatic, revenue-neutral way to help Americans pay down debt.
- Financial Aid Administrators
- Support the measure for bringing transparency and predictability to the cost of borrowing for higher education.
- Consumer Protection Advocates
- View the rate cap as essential relief for borrowers trapped in compounding debt amid a chaotic repayment system.
Perspectives this story doesn't cover
- Private Student Loan Lenders
- Federal Budget Deficit Hawks
Sources
Source coverage
2 outlets
3 viewpoints surfaced
- [1]The College Investor
Bipartisan Bills Propose 0% or 2% Student Loan Interest Rates
Read on The College Investor → - [2]NASFAAFinancial Aid Administrators
NASFAA Endorses Bipartisan Legislation to Create Fixed 2% Interest Rate on Federal Direct Student Loans
Read on NASFAA →
More in Education
See all →Student Debt
Parent PLUS Loans: Adverse Credit Checks, Endorser Rules, and Repayment Options
2 sources
Student Debt
Why Student Loan Refinancing Lowers Interest Rates but Costs Federal Borrower Protections
4 sources
Student Debt
IDR Forgiveness Becomes Taxable Again, Forcing Borrowers to Plan for Major Tax Bill
4 sources
Student Debt
Education Department Eliminates PSLF Grace Period, Mandates 'On-Time' Payments for Forgiveness and RAP Subsidy
6 sources
Comments
Every angle. Every day.
Get Education stories with full source coverage and perspective breakdowns, free every day.