
Global Sugar Prices Hit 15-Month High as El Niño and Ethanol Demand Squeeze Supply
Benchmark sugar futures have reached their highest levels since early 2025, driven by weather disruptions in Asia and Brazil's increasing diversion of sugarcane into ethanol production.
By Kabir Mehra
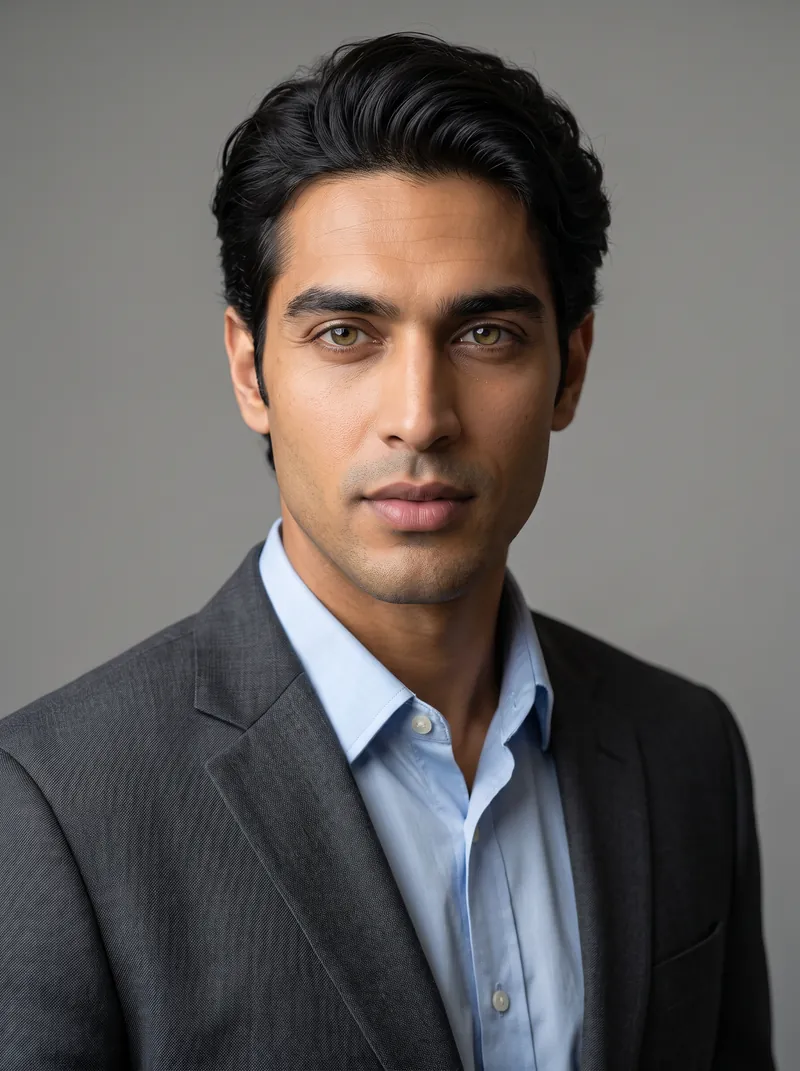
The cost of a morning pastry, a perfectly glazed doughnut, or a simple cup of sweetened coffee is quietly being rewritten by forces thousands of miles away. For bakers standing at their workbenches and everyday consumers walking the grocery aisles, the price of sugar is a foundational metric. When that metric spikes, the effects ripple through the entire food system, forcing manufacturers to either absorb the blow or pass the cost directly to your checkout receipt.
That spike has officially arrived. In August 2026, benchmark global sugar futures surged to a 15-month high, with New York raw sugar contracts climbing past 17 cents per pound and London white sugar reaching levels unseen since early 2025. The rally reflects a sudden, sharp tightening of global supplies, driven by a convergence of extreme weather patterns and shifting energy policies in the world's top producing nations.[3][4]
To understand why the cost of baking ingredients is climbing, you have to look at the mechanics of the Brazilian sugarcane industry. Brazil is the world's undisputed heavyweight in sugar production, but its sprawling, sun-drenched mills do not solely produce food. Sugarcane is a highly flexible, dual-purpose crop that can be crushed to extract sweet crystal sugar or fermented to produce ethanol—a biofuel that powers millions of vehicles across South America.[1][5]
This dual-use nature means the global sugar market is inextricably linked to the energy sector. When crude oil prices rise or domestic biofuel mandates increase, Brazilian mill operators pivot their massive crushing machinery to maximize ethanol output, which often yields a higher profit margin. In recent months, that shift has accelerated dramatically. By mid-2026, nearly 58 percent of Brazil's cane juice was being diverted away from the food supply and pumped directly into ethanol production.[2]
This massive diversion acts as a structural drain on the global food chain. As Brazil raises its mandatory ethanol blending targets to 32 percent, millions of tons of potential sugar are effectively burned as fuel instead of being shipped to bakeries and food processors worldwide. This energy-driven deficit is the first major pillar supporting the current price rally, turning a food staple into a combustible commodity.[2]
The second pillar is meteorological. The El Niño-Southern Oscillation (ENSO) is a cyclical climate pattern that warms the Pacific Ocean and disrupts global weather, often bringing parched, cracked earth to South and Southeast Asia while dumping excessive rainfall on parts of South America. For sugarcane—a crop that requires precise, predictable moisture levels during its growth and maturation phases—these disruptions are highly consequential.[6][7]
Sugarcane yield is not just about the physical volume of the green stalks hauled out of the fields; it is measured by 'total recoverable sugar' (TRS), which dictates how much actual sucrose can be extracted. Agronomic studies from the University of São Paulo demonstrate that while El Niño can sometimes boost the raw tonnage of cane in Brazil due to heavy rains, the excess water dilutes the sucrose concentration, consistently reducing the TRS across major growing regions.[6]
While Brazil manages diluted, water-logged yields, producers in Asia face a much more severe threat. El Niño typically brings blistering heat and dry conditions to India and Thailand, the world's second and third-largest sugar exporters. In India, deficient monsoon rainfall has stunted cane development, leaving fields dry and raising alarms about a significant drop in the upcoming harvest.[3][5]
Faced with a shrinking crop, the Indian government has prioritized domestic food security and its own aggressive biofuel targets over international trade. India has effectively halted sugar exports, a protective policy stance expected to remain in place through the 2026-27 marketing season. This removes a massive, critical buffer from the global market, leaving importing nations scrambling to secure alternative supplies.[1][7]
India's own domestic ethanol ambitions further complicate the picture. The country is pushing toward a 20 percent ethanol blending mandate, which requires diverting millions of tons of sugar into fuel production. Industry leaders warn that without significant price support for ethanol, mills might abandon biofuel manufacturing, but the current policy strictly limits the amount of sugar available to fill the global food sector's deficit.[1][5]
The combination of Brazil's ethanol pivot and India's export freeze has led commodity analysts to drastically revise their forecasts. Major trading houses that previously predicted a comfortable global sugar surplus for the 2026/27 season are now projecting deficits ranging from 300,000 to over 3 million metric tons. However, these projections remain highly sensitive to late-season weather developments and potential last-minute policy interventions.[3][4]
For the baking and beverage industries, this tightening supply signals a prolonged period of elevated costs. While governments may attempt to ease the pressure by cutting import duties or releasing strategic reserves, the fundamental mechanics of the market—where the food on your plate directly competes with the fuel in your tank under the shadow of a changing climate—suggest that cheap sugar may be a relic of the past.[1][4]
Perspectives explored
The Energy Sector's View
Biofuel advocates see sugarcane as a vital tool for energy independence and decarbonization.
For the energy sector, diverting sugarcane into ethanol is a necessary step toward reducing reliance on fossil fuels and meeting aggressive climate targets. Proponents argue that flexible milling infrastructure allows countries like Brazil and India to insulate themselves from volatile crude oil markets. From this perspective, the resulting tightness in the food supply is a secondary consequence of a much larger and more critical transition toward renewable energy and national fuel security.
The Food Industry's View
Food manufacturers and bakers view the diversion of sugar as a direct threat to affordable consumer goods.
Food processors and commercial bakeries argue that prioritizing biofuel over food extracts a heavy toll on the global supply chain. When governments mandate higher ethanol blending, they effectively artificially constrain the supply of a foundational culinary ingredient. This camp emphasizes that sustained high sugar prices inevitably lead to shrinkflation, recipe reformulation, or direct price hikes passed on to consumers, disproportionately affecting the economics of the baking and beverage sectors.
The Agronomic View
Agricultural scientists focus on the physical limitations of the crop under changing climate conditions.
Researchers emphasize that market policies are secondary to the physical realities of climate patterns like El Niño. Even if mills wanted to produce more sugar, the agronomic data shows that extreme weather alters the plant's biology, specifically reducing the total recoverable sucrose (TRS) within the stalks. This viewpoint argues that the market must price in a permanent risk premium, as volatile weather patterns make it increasingly difficult to guarantee consistent yields regardless of whether the end product is food or fuel.
Key points
- Global sugar futures have reached a 15-month high, driven by tightening supplies and shifting production priorities.
- Brazil is diverting nearly 58 percent of its sugarcane juice into ethanol fuel, significantly reducing its sugar exports.
- El Niño weather patterns have stunted cane development in India and Thailand, threatening the upcoming harvest.
- India has effectively halted sugar exports to protect domestic supplies and meet its own aggressive biofuel mandates.
Open questions
- It remains unclear exactly how much the upcoming Asian harvest will underperform, as late-season rains could still marginally improve yields.
- The degree to which major food manufacturers will pass these elevated raw material costs directly to consumers versus absorbing them through recipe reformulation is still unfolding.
Timeline
Early 2025
Global sugar prices experience a brief period of stabilization following a record harvest in Brazil.
Late 2025
The El Niño climate pattern intensifies, bringing severe drought to key growing regions in India and Thailand.
June 2026
Brazil accelerates its biofuel push, diverting nearly 58 percent of its sugarcane juice into ethanol production.
August 2026
Benchmark global sugar futures surge to a 15-month high as analysts revise their 2026/27 forecasts from a surplus to a structural deficit.
- Agricultural Producers
- Prioritizes crop yields, weather impacts, and the operational trade-offs between food and fuel production.
- Commodity Analysts
- Focuses on futures pricing, supply deficits, and the macroeconomic indicators driving the market.
- Climate & Trade Researchers
- Examines the long-term structural shifts caused by cyclical weather patterns and national biofuel mandates.
Perspectives this story doesn't cover
- Small-scale independent bakeries
- Consumer advocacy groups
Sources
Source coverage
7 outlets
3 viewpoints surfaced


- [1]S&P GlobalAgricultural Producers
India warns ethanol output faces collapse. Brazil shifts more cane to fuel production. El Nino threatens global sugar supply cuts.
Read on S&P Global → - [2]The Economic TimesAgricultural Producers
Sugar stocks rallied for a second session on Friday as domestic sugar prices climbed 8-10% over the past month to a seven-year high
Read on The Economic Times → - [3]BarchartCommodity Analysts
Sugar prices extended this month's sharp rally on Tuesday, with NY sugar posting a 15-month high
Read on Barchart → - [4]ChiniMandiAgricultural Producers
Global and Indian sugar prices have climbed sharply, with concerns over production in major growing regions
Read on ChiniMandi → - [5]International Food Policy Research InstituteClimate & Trade Researchers
Déjà vu all over again: Global sugar markets roiled by El Niño, biofuels and trade policies
Read on International Food Policy Research Institute → - [6]University of São PauloClimate & Trade Researchers
The El Niño-Southern Oscillation (ENSO) is a major driver of interannual climate variability worldwide
Read on University of São Paulo → - [7]Business StandardAgricultural Producers
India's sugar industry is entering a structural shift
Read on Business Standard →
More in Food & Drink
See all →Baking Science
The 60°C to 85°C Window: How Starch Gelatinization Sets the Crumb Structure and Defines a Baked Good's Final Texture
6 sources
Sodium Bicarbonate
The Alkaline-Acid Collision: How Sodium Bicarbonate Demands a Low-pH Partner to Aerate Crumb Structure
6 sources
Baking Chemistry
The Hygroscopic Tug-of-War: How Sucrose Steals Water from Gluten to Build a Tender Cake
9 sources
Sourdough Microbiome
How Flour Choice and Wheat Enzymes Dictate the Microbiome and Digestibility of Sourdough
7 sources
Comments
Every angle. Every day.
Get Food & Drink stories with full source coverage and perspective breakdowns, free every day.