
OpenAI's Q2 Sales Growth Lags Rival Anthropic, Raising Concerns Over AI Valuation Bubble
Anthropic more than doubled its second-quarter revenue to $11.6 billion and achieved operating profitability, while OpenAI's growth slowed to 18% as losses widened to $12.3 billion.
The prevailing assumption across Wall Street has been that frontier artificial intelligence is a race to the bottom—a capital-incinerating contest where companies must subsidize users for years before seeing a dime of profit. The second-quarter financial disclosures from the industry's two biggest private players just shattered that consensus, but not in the direction most expected.[5]
OpenAI, long considered the undisputed leader of the generative AI boom, reported that its second-quarter revenue grew by just 18% quarter-over-quarter to $6.7 billion. For a company priced for hypergrowth, the sequential deceleration has alarmed shareholders who expected the startup to maintain its dominant market trajectory.[1][4]
Compounding the sluggish top-line growth, OpenAI's operating losses widened significantly. The company reported a $12.3 billion operating loss for the quarter, up from $9.3 billion in the first quarter. This pushes the ChatGPT maker further away from profitability just as the broader market begins to demand sustainable unit economics.[1]
In stark contrast, rival Anthropic more than doubled its revenue over the same period, reaching $11.6 billion. This represents a staggering 14-fold increase from the $787 million the company recorded in the second quarter of 2025, marking a rapid acceleration in its commercial footprint.[1][6]
More importantly, Anthropic reported a positive adjusted operating profit of approximately $559 million. This marks a historic milestone for the sector, challenging the entrenched thesis that leading AI models must remain money-losing loss leaders to capture market share.[5][6]
The divergence between the two AI giants stems from a fundamental shift in enterprise adoption. While OpenAI has faced slower growth for its flagship ChatGPT product, Anthropic's Claude Code has gained massive traction among software developers and corporate IT departments.[1][3]
Anthropic has aggressively targeted the enterprise API market, focusing on reliability, extended context windows, and advanced coding capabilities. By mid-2026, data from corporate payment processors indicated that a larger share of U.S. enterprises were actively paying for Anthropic's services than OpenAI's.[3]
This financial decoupling is forcing a rapid reassessment of the so-called "AI valuation bubble." The bubble thesis rests on the idea that AI companies are raising capital at astronomical valuations without a viable path to generating free cash flow.[2][5]
OpenAI's current trajectory exemplifies this risk. The company has reportedly locked in an estimated $1.4 trillion in long-term spending commitments, including massive deals with Microsoft and Oracle. These commitments were made under the assumption of exponential, uninterrupted revenue growth.[1][3]
With OpenAI's growth rate decelerating on a smaller revenue base than its chief rival, those capital commitments now look increasingly precarious. The widening gap between revenue and compute costs raises serious questions about the sustainability of its $882 billion private market valuation.[3][4]
Conversely, Anthropic's newfound profitability is fueling unprecedented valuation targets. The company is reportedly preparing for an October 2026 initial public offering that could value the firm at up to $2 trillion.[2][6]
If realized, an Anthropic IPO at that scale would eclipse SpaceX's recent listing to become the largest public debut in history. Investors are modeling the valuation on forward projections that Anthropic's annualized revenue run rate could reach $100 billion to $120 billion by the end of 2026.[2][6]
Because both OpenAI and Anthropic remain private, the immediate market impact is rippling through their publicly traded proxies and infrastructure partners. Microsoft, which holds significant exposure to OpenAI through investments and Azure cloud workloads, faces heightened scrutiny over whether its AI capital expenditures will yield the expected returns.[3][4]
Meanwhile, Anthropic's success is validating the massive data-center investments made by its primary backers, Amazon and Alphabet. The ability of an AI lab to generate positive operating income makes the hyperscalers' AI-linked debt and infrastructure spending look far more defensible to skeptical shareholders.[5]
The critical unknown moving forward is whether Anthropic's profitability is a durable structural advantage or a temporary artifact of its accounting practices. The company's adjusted operating income excludes certain stock-based compensation, and the underlying economics of its custom silicon partnerships remain opaque.[1][5]
Furthermore, the sheer scale of capital required to train the next generation of frontier models means that even a profitable quarter does not eliminate the need for massive ongoing fundraising. Both companies are locked in an arms race that demands tens of billions of dollars in specialized semiconductors and energy infrastructure.[2][4]
Key points
- Anthropic's Q2 revenue reached $11.6 billion, more than doubling its previous quarter.
- OpenAI reported 18% sequential revenue growth to $6.7 billion, alongside a $12.3 billion operating loss.
- Anthropic achieved a positive adjusted operating profit of approximately $559 million.
- Investors project Anthropic could seek a $2 trillion valuation in an October 2026 IPO.
What we don’t know
- Whether Anthropic's adjusted operating profit will remain positive once all stock-based compensation is factored in.
- How OpenAI plans to restructure its $1.4 trillion in spending commitments given its slower revenue growth.
- If the broader market will support a $2 trillion valuation for Anthropic during its anticipated October IPO.
How we got here
March 2026
OpenAI closes a $122 billion funding round, pushing its private valuation to $852 billion.
May 2026
Anthropic announces a $65 billion Series H round, reaching a $965 billion valuation and surpassing OpenAI.
June 2026
Anthropic confidentially files its S-1 application with the SEC, preparing for a public listing.
August 2026
Q2 financials reveal Anthropic's $11.6 billion revenue and positive operating profit against OpenAI's widening $12.3 billion loss.
October 2026
Anthropic targets a historic initial public offering that could value the company at up to $2 trillion.
- AI Infrastructure Bulls
- Argue that Anthropic's profitability validates the massive capital expenditures by hyperscalers, proving the AI business model works.
- Valuation Skeptics
- Warn that pricing a company at $2 trillion based on forward projections while the sector still burns massive cash is the definition of a bubble.
- Enterprise Adopters
- Prioritize model reliability, coding capabilities, and data security, driving the market shift away from consumer chatbots toward specialized APIs.
Perspectives this story doesn't cover
- Open-Source AI Developers
- Retail Investors
Sources
Source coverage
6 outlets
3 viewpoints surfaced

- [1]Investing.comEnterprise Adopters
OpenAI's Q2 revenue growth lagged Anthropic as losses deepened, WSJ reports
Read on Investing.com → - [2]ForbesValuation Skeptics
Anthropic Eyed For $2 Trillion IPO Valuation
Read on Forbes → - [3]TradingViewEnterprise Adopters
OpenAI's Revenue Growth Reportedly Slows As Anthropic Pulls Ahead – Which AI Stocks Could Feel The Ripple Effects?
Read on TradingView → - [4]NewsquawkValuation Skeptics
OpenAI's Q2 sales show tepid growth compared with Anthropic, according to WSJ
Read on Newsquawk → - [5]Seeking AlphaAI Infrastructure Bulls
The Math Of The AI Bubble Is Changing
Read on Seeking Alpha → - [6]AlphaMatchAI Infrastructure Bulls
The Rise of Anthropic: From Startup to Profit Powerhouse
Read on AlphaMatch →
More in Finance
See all →Risk-Free Rate
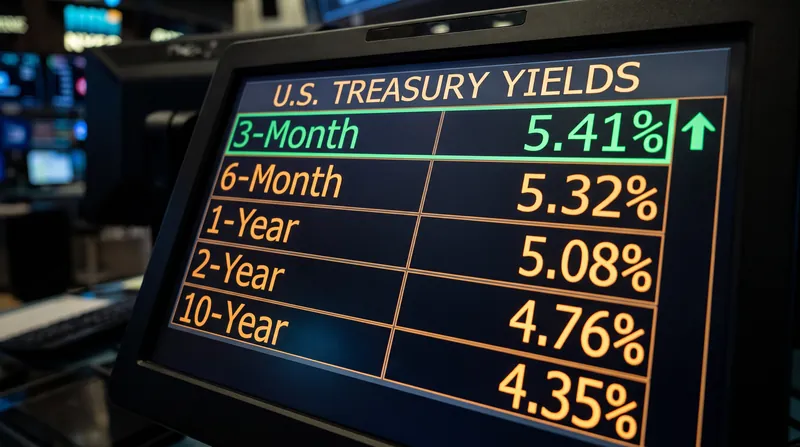
The Near-Zero Duration and Minimal Default Risk That Make the 3-Month Treasury Bill the Standard Risk-Free Rate Proxy
9 sources
Derivatives Pricing
How Volatility, Time to Expiration, and the Risk-Free Rate Dictate the Theoretical Value of a European Option in the Black-Scholes Model
4 sources
AI Infrastructure
Nvidia Locks In $279 Billion Supply Commitment as AI Buildout Shifts From Silicon to Project Finance
5 sources
Risk Metrics
Why the Standard Deviation of Returns is the Denominator in the Sharpe Ratio, Not the Variance
6 sources
Comments
Every angle. Every day.
Get Finance stories with full source coverage and perspective breakdowns, free every day.