
Fed Chair Warsh Proposes Cutting FOMC Meetings From Eight to Six Per Year
Federal Reserve Chair Kevin Warsh has formally proposed reducing the central bank's policy-setting meetings to six per year, marking the biggest potential shift in monetary governance since 1981.
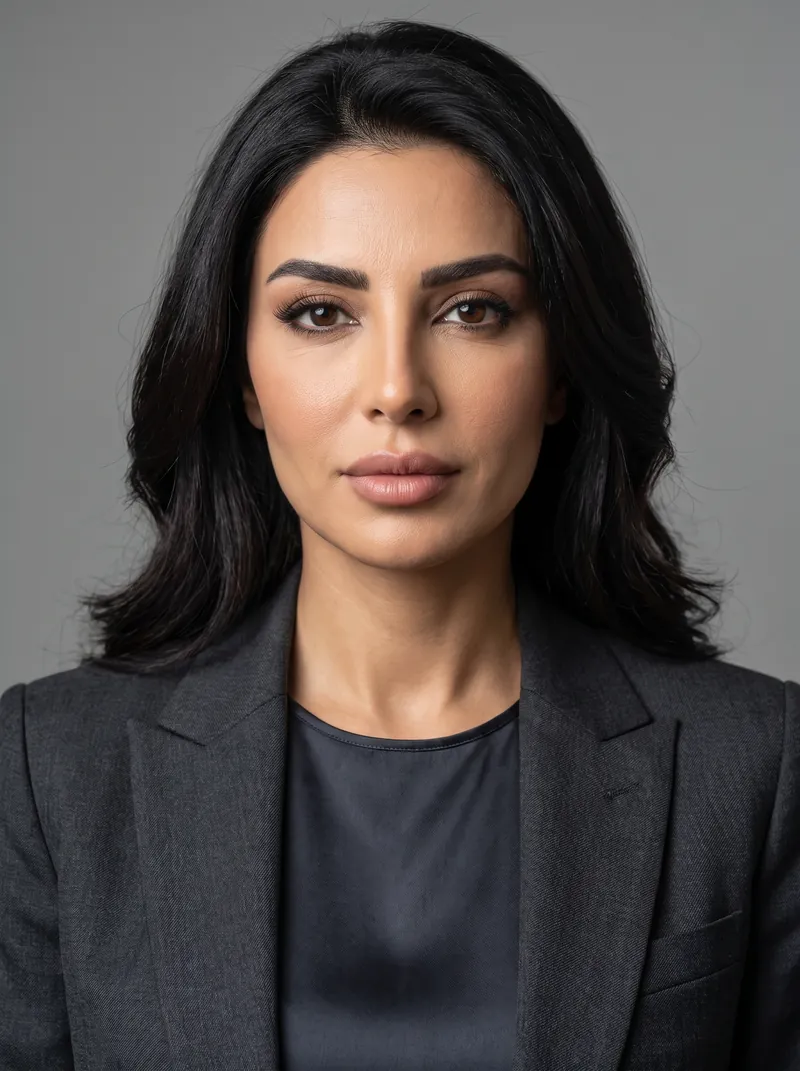
Most of Wall Street spent Wednesday dissecting a 9-to-3 vote. When the Federal Reserve released the minutes from its July 28–29 policy meeting, the headline takeaway was a trio of hawkish dissents pushing for an immediate rate hike while the majority held the federal funds rate at 3.50% to 3.75%.
But the market fixated on the immediate trajectory of borrowing costs entirely missed the structural earthquake buried deeper in the release. Chair Kevin Warsh formally proposed reducing the central bank's policy-setting meetings from eight per year to six, a procedural overhaul that would fundamentally alter how global markets price risk.[2][8]
The proposal, documented in the August 19 minutes, centers on extending the interval between interest rate decisions from roughly six weeks to approximately two months. Warsh argued that a six-meeting schedule would allow more economic data to accumulate between sessions, providing policymakers and staff with the necessary breathing room to evaluate broader strategic monetary policy issues rather than reflexively reacting to the latest monthly data print.[4][8]
The mechanics of the shift are legally straightforward but institutionally profound. The Banking Act of 1935 mandates a minimum of only four Federal Open Market Committee (FOMC) meetings annually, meaning no congressional approval is required to drop to six. However, the Federal Reserve has operated on a strict eight-meeting cadence since 1981, when former Chair Paul Volcker established the modern schedule. For 45 years, that rhythm has served as the foundational metronome for the global financial system.[2][3][5]
The practical stakes for corporate treasurers and retail investors are immediate. The FOMC calendar functions as a series of informational checkpoints where markets receive updated guidance on the cost of capital. Removing two of those checkpoints means investors will have to navigate longer, nine-week stretches of policy silence. Analysts warn this could lift the term premium on 10- and 30-year Treasury yields, as bondholders demand greater compensation for the increased uncertainty of holding debt through extended periods without central bank communication.[1][5]
The move aligns perfectly with Warsh's long-standing advocacy for a "quieter Fed." Since taking office, he has systematically dismantled the era of explicit forward guidance, arguing that central banks preserve credibility and independence by communicating sparingly but decisively. This philosophy is not new for Warsh; in 2014, while reviewing monetary policy transparency for the Bank of England, he successfully recommended reducing their meeting frequency from 12 times a year to eight.[3][5]
For markets, the reduction in meetings would create a compounding deficit of policy signals. A six-meeting schedule would likely eliminate the quarterly Summary of Economic Projections (SEP) at alternate meetings, directly reducing the frequency of the closely watched "dot plot" that outlines policymakers' rate outlooks. Combined with Warsh's explicit reluctance to offer forward guidance, the financial system is facing a structural shift toward a central bank that speaks less often and offers fewer clues when it does.[2][7]
Critics of the proposal argue that stretching the gap between meetings could leave the Fed dangerously flat-footed. During periods of rapid macroeconomic shifts—such as sudden spikes in inflation or unexpected deterioration in the labor market—a nine-week interval is an eternity. While the FOMC retains the authority to convene unscheduled emergency meetings, as it did during the onset of the pandemic in March 2020, those interventions are historically reserved for severe financial crises rather than standard policy recalibrations.[3][5][8]
As of now, the proposal remains a discussion point rather than a finalized directive. The committee reached no formal conclusion during the July session, and Warsh explicitly noted that the remaining 2026 schedule of eight meetings will proceed unchanged. However, with internal task forces currently reviewing the Fed's broader communication framework, Wall Street is already recalibrating its models for a six-meeting reality beginning in 2027.[2][4][8]
Viewpoints in depth
The 'Quieter Fed' Advocates
Proponents argue that fewer meetings reduce market overreaction to noisy data and allow the central bank to focus on long-term strategy.
This camp, heavily aligned with Chair Warsh's philosophy, believes the Federal Reserve has spent the last decade over-communicating. By providing constant forward guidance and meeting every six weeks, the Fed has trained markets to hang on every word, creating unnecessary volatility around minor data misses. They argue that a two-month interval forces both policymakers and investors to look at broader economic trends rather than reacting reflexively to a single month's inflation or payroll report.
Market Volatility Analysts
Financial strategists warn that longer gaps between meetings will increase uncertainty and drive up borrowing costs.
For bond traders and corporate treasurers, the eight-meeting schedule provides essential, regular checkpoints. This camp argues that removing two meetings does not reduce volatility; it simply delays and concentrates it. Without regular Fed communication, markets will be forced to over-index on interim data prints, potentially driving up the term premium on long-dated Treasuries as investors demand more compensation for holding debt through extended nine-week policy blackouts.
Institutional Traditionalists
Critics emphasize that the 45-year-old schedule provides necessary transparency and agility for the global financial system.
This perspective highlights the operational risks of a slower central bank. While the Fed can always call an emergency meeting, doing so inherently signals a crisis, which can trigger panic. Traditionalists argue that the standard six-week interval allows the FOMC to make incremental, boring adjustments to monetary policy. Stretching that to nine weeks risks leaving the committee flat-footed during rapid macroeconomic shifts, forcing them to make larger, more disruptive rate moves when they finally do convene.
Key points
- Fed Chair Kevin Warsh formally proposed reducing the FOMC's annual meeting schedule from eight to six starting in 2027.
- The shift would mark the most significant structural change to U.S. monetary policymaking since 1981.
- Warsh argues the longer intervals will allow more data to accumulate and foster strategic, rather than reactive, policy discussions.
- Analysts warn the change could increase market volatility by removing key informational checkpoints and reducing forward guidance.
How we got here
1935
Congress passes the Banking Act, establishing the modern FOMC structure and mandating a minimum of four meetings annually.
1981
Under Chair Paul Volcker, the Federal Reserve adopts its current schedule of eight policy meetings per year.
2014
Kevin Warsh advises the Bank of England to reduce its meeting frequency from 12 to eight times a year.
July 28-29, 2026
Chair Warsh formally proposes reducing the FOMC schedule to six meetings per year during the committee's policy session.
August 19, 2026
The release of the July FOMC minutes makes Warsh's proposal public, sparking debate across financial markets.
- Market Volatility Analysts
- Warn that longer gaps between meetings will increase uncertainty and drive up borrowing costs.
- Monetary Policy Minimalists
- Argue that fewer meetings reduce market overreaction to noisy data and allow the central bank to focus on long-term strategy.
- Institutional Traditionalists
- Emphasize that the 45-year-old schedule provides necessary transparency and agility for the global financial system.
Perspectives this story doesn't cover
- International Central Bankers
- Corporate Treasurers
Sources
Source coverage
8 outlets
3 viewpoints surfaced

- [1]Seeking AlphaMarket Volatility Analysts
Kevin Warsh may cut annual FOMC meetings from eight to six
Read on Seeking Alpha → - [2]Discovery AlertInstitutional Traditionalists
The Kevin Warsh Six FOMC Meetings Proposal: What the Minutes Actually Revealed
Read on Discovery Alert → - [3]ChosunMonetary Policy Minimalists
Warsh Proposes Cutting FOMC Meetings After 45 Years
Read on Chosun → - [4]Kitco NewsMarket Volatility Analysts
FOMC minutes show a Fed growing restless on inflation as Warsh floats six-meeting FOMC schedule for 2027
Read on Kitco News → - [5]ChaseInstitutional Traditionalists
Reports say Fed Chair Kevin Warsh is considering fewer FOMC meetings
Read on Chase → - [6]AxiosMonetary Policy Minimalists
Federal Reserve chairman Kevin Warsh is reportedly weighing whether the central bank should hold fewer policy meetings each year
Read on Axios → - [7]CryptoRankMarket Volatility Analysts
Fed Governor Warsh Proposes Reducing FOMC Meetings to Six Per Year
Read on CryptoRank → - [8]RiskStockInstitutional Traditionalists
Buried in the Fed Minutes: Warsh Wants to Cut FOMC Meetings From Eight to Six
Read on RiskStock →
More in Finance
See all →Fed Watch
Fed Governor Waller Signals September Rate Hold, Citing Skewed Nonmarket Services Inflation
6 sources
Fed Watch
Bond Market Turmoil Intensifies as Fed Signals Jackson Hole Speech Will Avoid Rate Guidance
3 sources
Inflation Watch
Core CPI 3-Month Annualized Rate Falls Below 2% Target for First Time Since 2025
7 sources
Inflation Metrics
The Weighting and Substitution Differences That Make the PCE the Federal Reserve's Preferred Inflation Gauge
7 sources
Comments
Every angle. Every day.
Get Finance stories with full source coverage and perspective breakdowns, free every day.