
Federal Reserve Makes AI a Central Focus of Monetary Policy, Citing 'Hinge Point in History'
Federal Reserve Chair Kevin Warsh used the Jackson Hole symposium to formally integrate artificial intelligence into the central bank's macroeconomic baseline, signaling a historic shift in how policymakers model productivity, inflation, and labor.
Share this story
At 10:00 a.m. Mountain Time on Friday, Federal Reserve Chair Kevin Warsh stepped to the podium at the Jackson Hole Economic Symposium and formally altered the central bank's macroeconomic baseline. Delivering a highly anticipated keynote, Warsh declared the global economy has reached a "hinge point in history" driven by the rapid deployment of artificial intelligence.[1]
The address marked a definitive departure from the Fed’s traditional reliance on backward-looking labor and inflation metrics. Instead, Warsh charted a forward-looking path that explicitly integrates the deflationary pressures of automation and the inflationary pressures of massive capital expenditure into the Federal Open Market Committee’s policy framework.[1]
For decades, central bankers have treated technological advancement as a slow-moving background variable. By elevating AI to a central pillar of monetary policy, the Fed is acknowledging that the current wave of technological integration is moving too fast to be ignored in real-time rate decisions.[1][2]
The mechanism through which AI alters monetary policy centers on productivity growth. If generative AI and advanced automation allow companies to produce more output with fewer hours worked, the economy's theoretical "speed limit" increases, fundamentally changing the calculus for the neutral rate of interest.[1]
In a high-productivity environment, the economy can run hotter—sustaining stronger wage growth and higher corporate profits—without triggering the kind of runaway inflation that forces the central bank to aggressively hike interest rates.[6]
However, this transition is not seamless. The blistering pace of corporate earnings growth, driven largely by efficiency gains and tech sector dominance, is masking underlying fractures in the broader economy that complicate the Fed's dual mandate.[6]
Market dynamics reflect this severe bifurcation. The S&P 500 has continued to climb even on days when the vast majority of individual stocks struggle, heavily propped up by a small club of mega-cap technology firms that are building the infrastructure for the AI boom.[3]
This intense concentration of capital creates a unique challenge for monetary policymakers. The Fed must set a single interest rate for an economy that is effectively operating on two different tracks: a hyper-capitalized tech sector and a traditional economy grappling with higher borrowing costs.[3]
The labor market is already showing signs of this structural shift. While the U.S. labor market appeared to be on an upswing earlier in the year, hiring has slowed significantly over the summer, and the volume of help-wanted advertisements has contracted sharply.[4]
Economists are debating whether this hiring slowdown is a temporary cyclical dip or the early stages of AI-driven labor displacement. If companies are substituting software for white-collar labor, the traditional relationship between economic growth and job creation may be fundamentally weakening.[4]
Warsh's pivot at Jackson Hole also carries immediate political ramifications. By signaling that the structural changes brought by AI might require the Fed to maintain a tighter policy stance to manage the massive capital investments flowing into data centers and energy infrastructure, Warsh is setting up a clash with the White House.[2]
The administration has been vocal about its desire for a reduction in borrowing costs ahead of the midterm elections. Warsh’s forward-looking framework, which prioritizes long-term stability over short-term stimulus, runs directly counter to the political demand for immediate rate cuts.[2]
Furthermore, the sheer scale of government and corporate borrowing required to fund the next generation of technological infrastructure is raising concerns about a new age of financial repression.[5]
Financial repression occurs when policies are implemented to channel funds to the government, often resulting in negative real returns for savers. As the U.S. issues more debt to subsidize domestic semiconductor manufacturing and energy grids, the pressure on the bond market intensifies.[5]
The idea of effectively forcing investors to absorb massive quantities of U.S. government bonds is gaining traction as a necessary evil to fund the geopolitical race for AI supremacy, complicating the Fed's balance sheet reduction efforts.[5]
For retail investors and corporate treasurers alike, the Fed's new framework introduces a novel layer of complexity. Traditional economic indicators, such as the monthly non-farm payrolls report, may trigger unconventional market reactions if investors believe the Fed is viewing the data through an AI-adjusted lens.[1][4]
If a weak jobs report is interpreted as a sign of rising productivity rather than a looming recession, the central bank may choose to hold rates steady rather than rushing to cut them, upending decades of market conditioning.[4]
Ultimately, the Jackson Hole address will be remembered as the moment the Federal Reserve officially recognized that the architecture of the 21st-century economy has changed. Navigating this "hinge point" will require policymakers to rely on real-time data analytics and a willingness to discard models that no longer fit reality.[1]
Key points
- Fed Chair Kevin Warsh declared AI a 'hinge point in history' that will fundamentally alter monetary policy.
- The central bank is shifting from backward-looking labor metrics to forward-looking productivity and automation models.
- A severe divergence has emerged between soaring tech-driven corporate earnings and a slowing broader labor market.
- The Fed's stance puts it on a collision course with the White House, which desires lower borrowing costs ahead of the midterms.
What we don’t know
- Whether the current slowdown in hiring is a temporary cyclical dip or the beginning of permanent AI-driven labor displacement.
- Exactly how much AI will increase the neutral rate of interest (R-star) over the next decade.
- How financial markets will react if the Fed begins interpreting weak jobs data as a positive sign of rising productivity.
How we got here
Nov 2022
The public release of advanced generative AI models sparks a global race for technological dominance.
Mid 2024
Technology mega-caps begin unprecedented capital expenditure cycles to build out data centers and energy infrastructure.
Early 2026
The U.S. labor market shows initial signs of decoupling from corporate earnings growth as hiring slows.
Aug 2026
Fed Chair Warsh formally integrates AI productivity metrics into the central bank's monetary policy framework at Jackson Hole.
- Monetary Hawks
- Argue that the massive capital expenditure required for AI infrastructure will be inherently inflationary, necessitating higher interest rates.
- Tech Optimists
- Believe AI will trigger a historic productivity boom, allowing the economy to grow faster without generating inflation.
- Labor Economists
- Warn that the current hiring slowdown is structural, as corporations substitute software for white-collar labor to protect margins.
Perspectives this story doesn't cover
- Small Business Owners
- Displaced White-Collar Workers
Sources
Source coverage
6 outlets
3 viewpoints surfaced
- [1]Financial TimesMonetary Hawks
Warsh charts a forward-looking path for the Fed at Jackson Hole
Read on Financial Times → - [2]Financial TimesMonetary Hawks
Warsh puts Fed on collision course with Trump ahead of midterms
Read on Financial Times → - [3]MarketWatchLabor Economists
The S&P 500 keeps climbing on days when stocks broadly struggle. Here’s what’s going on.
Read on MarketWatch → - [4]MarketWatchLabor Economists
Where are all the new jobs? Hiring slows again — and it probably won’t speed up soon.
Read on MarketWatch → - [5]Financial TimesMonetary Hawks
Risk of a new age of financial repression is rising
Read on Financial Times → - [6]MarketWatchLabor Economists
Corporate earnings have been growing at a blistering pace. Here’s why that’s not likely to last.
Read on MarketWatch →
More in Finance
See all →Sanctions Enforcement
US Treasury Sanctions Iranian Crypto Exchange BitBank Over Hormuz Transit Payments
6 sources
Market Mechanics
How Market Depth and Price-Time Priority Dictate the Execution Price of a Large Market Order
6 sources
Portfolio Theory
Using Capital Allocation Lines to Maximize Returns Along the Efficient Frontier
4 sources
Risk-Free Rate
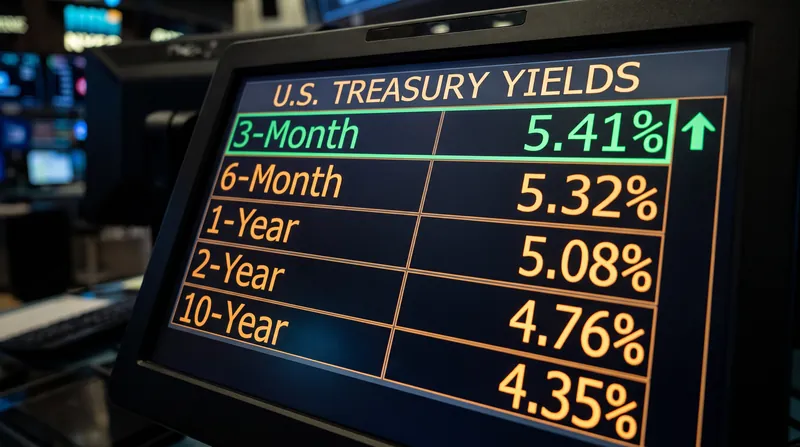
The Near-Zero Duration and Minimal Default Risk That Make the 3-Month Treasury Bill the Standard Risk-Free Rate Proxy
7 sources
Comments
Every angle. Every day.
Get Finance stories with full source coverage and perspective breakdowns, free every day.