
full timeline
US commercial real estate downturn
A $70 million distressed sale of Philadelphia's Centre Square complex has wiped out junior debt and inflicted rare losses on top-rated commercial mortgage bonds.
Follow US commercial real estate downturn in the Factlen app and get an alert when there is news. Get the app
Share this story
Latest report
US Commercial Real Estate Losses Breach AAA-Rated CMBS Tranches as Treasury Yields Surge
A $70 million distressed sale of Philadelphia's Centre Square complex has wiped out junior debt and inflicted rare losses on top-rated commercial mortgage bonds. The 85 percent valuation drop highlights mounting refinancing pressures across the office sector as elevated borrowing costs persist.
- A federal judge approved the $70 million sale of Philadelphia's Centre Square complex, an 85 percent drop from its 2019 valuation.
- The distressed sale wipes out seven junior debt tranches and inflicts rare losses on the AAA-rated senior bond.
- PIMCO faces more than $35 million in losses on its $58 million position in the single-asset commercial mortgage-backed security.
- The property's occupancy fell from 93 percent in early 2020 to just 28 percent by June 2026.
- The new owners plan to convert portions of the office complex into a 300-room luxury hotel and 500 residential apartments.
When the Palisades Center mall in New York saw its valuation collapse last year, it marked only the second time since the 2008 financial crisis that losses reached the AAA-rated tranche of a commercial mortgage-backed security. Now, a distressed sale in downtown Philadelphia has triggered the third, but this time the catalyst is not a shifting retail landscape—it is the collision of remote work and a 5 percent Treasury yield environment that has fundamentally reset the cost of commercial borrowing.[3][7]
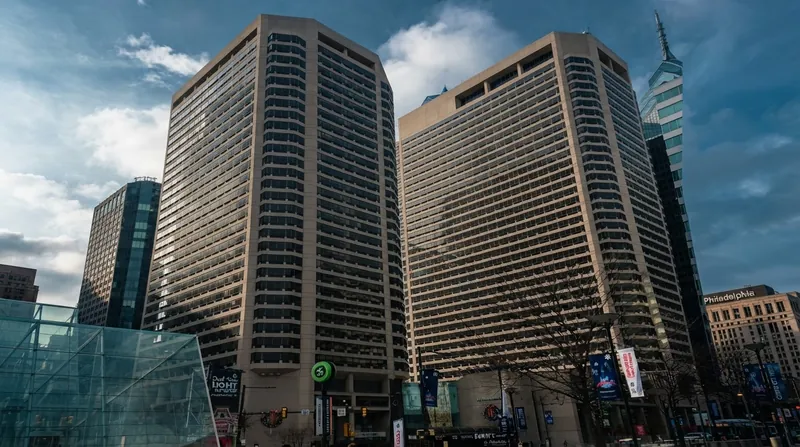
A federal judge approved the sale of the 1.8-million-square-foot Centre Square office complex for $70 million in late August 2026, clearing the way for a transaction that wipes out seven junior debt tranches. The two-tower property, located directly across from Philadelphia's City Hall, was appraised at $471 million in 2019 before the pandemic emptied its corridors. The resulting 85 percent decline in value means that even the safest slice of the $368 million CMBS loan—originally rated AAA—will absorb a severe financial hit.[1][2][4][6][7]
Pacific Investment Management Co. (PIMCO), which holds roughly $58 million in face value across the deal, faces investment losses exceeding $35 million. Wall Street strategists project that the senior debt tranche will recover approximately 44 cents on the dollar once advances, fees, and other claims are settled. The borrower initially defaulted after failing to secure refinancing when the loan matured in 2022, leading to foreclosure and the eventual court-ordered sale to PMC Property Group and developer Dean Adler.[1][2][4][6][7]
The timeline of the Centre Square default illustrates the speed of the commercial office correction. When the mortgage was refinanced and securitized into a bond just weeks before the COVID-19 pandemic in early 2020, the complex was 93 percent leased to 56 different tenants. By the end of June 2026, servicer commentary indicated that occupancy had plummeted to just 28 percent, leaving the property incapable of generating the cash flow required to service its debt.[2][7]
The transaction highlights a structural vulnerability in a specific type of commercial real estate debt. The Centre Square bond was a single-asset, single-borrower (SASB) deal, a financing vehicle that surged in popularity over the last decade. Unlike traditional CMBS pools that bundle dozens of mortgages across different property types and regions to dilute risk, an SASB relies entirely on one complex. When that single property fails, the bond lacks the diversification necessary to absorb the shock, pushing losses straight up the capital stack.[2][4][7]
The broader commercial real estate market is grappling with similar pressures as a massive wall of maturing debt collides with elevated interest rates. Treasury yields surging above 5 percent have dramatically increased the cost of capital for property owners seeking to refinance. In August 2026 alone, Morningstar DBRS downgraded 112 classes across 25 North American CMBS transactions, citing office-sector weakness, declining debt service coverage ratios, and significant valuation impairments.[3][5]
For prospective buyers and current owners navigating the commercial market, the Centre Square sale establishes a stark new baseline for price discovery. The buyers plan to convert portions of the 1974-built complex into a 300-room luxury hotel and up to 500 residential apartments, retaining only a fraction of the original office footprint. This adaptive reuse strategy reflects a growing consensus that older, single-tenant-reliant office buildings in major urban centers may never recover their pre-2020 valuations.[4][7]
Financial analysts warn that the pain in the SASB market is likely far from over, with more than 30 top-rated slices of SASB CMBS deals currently trading below 85 cents on the dollar.
“In places like Chicago, downtown Los Angeles, Portland, Denver, the values of office real estate have not bounced back,” said Alan Todd, head of CMBS strategy at Bank of America Corp. “You're definitely going to see more of this. Over the next year or two, more of these loans will come due and borrowers will run out of options.”[2][7]
Sources
- [1]Investing.com — CMBS Losses Reach the AAA Tranche Again Read on Investing.com →
- [2]Real Investment Advice — CMBS Losses Reach The AAA Tranche Again Read on Real Investment Advice →
- [3]CRE Daily — Treasury Yields Above 5% Reset CRE Borrowing Costs Read on CRE Daily →
- [4]CRE Daily — Centre Square CMBS Sale Wipes Out Lower Debt Tranches Read on CRE Daily →
- [5]Morningstar DBRS — Morningstar DBRS Releases Monthly North American CMBS Rating Action Summary for August 2026 Read on Morningstar DBRS →
- [6]The Real Deal — PIMCO faces $35M loss on Centre Square CMBS Read on The Real Deal →
- [7]Swissinfo — Pimco faces severe losses on Centre Square CMBS Read on Swissinfo →
Charts, maps and images
Timeline
September 2026
US Commercial Real Estate Losses Breach AAA-Rated CMBS Tranches as Treasury Yields Surge
August 2026
The 79% Reset: What the $70M Sale of Philadelphia's Largest Office Tower Reveals About the Commercial Real Estate Correction
AI
